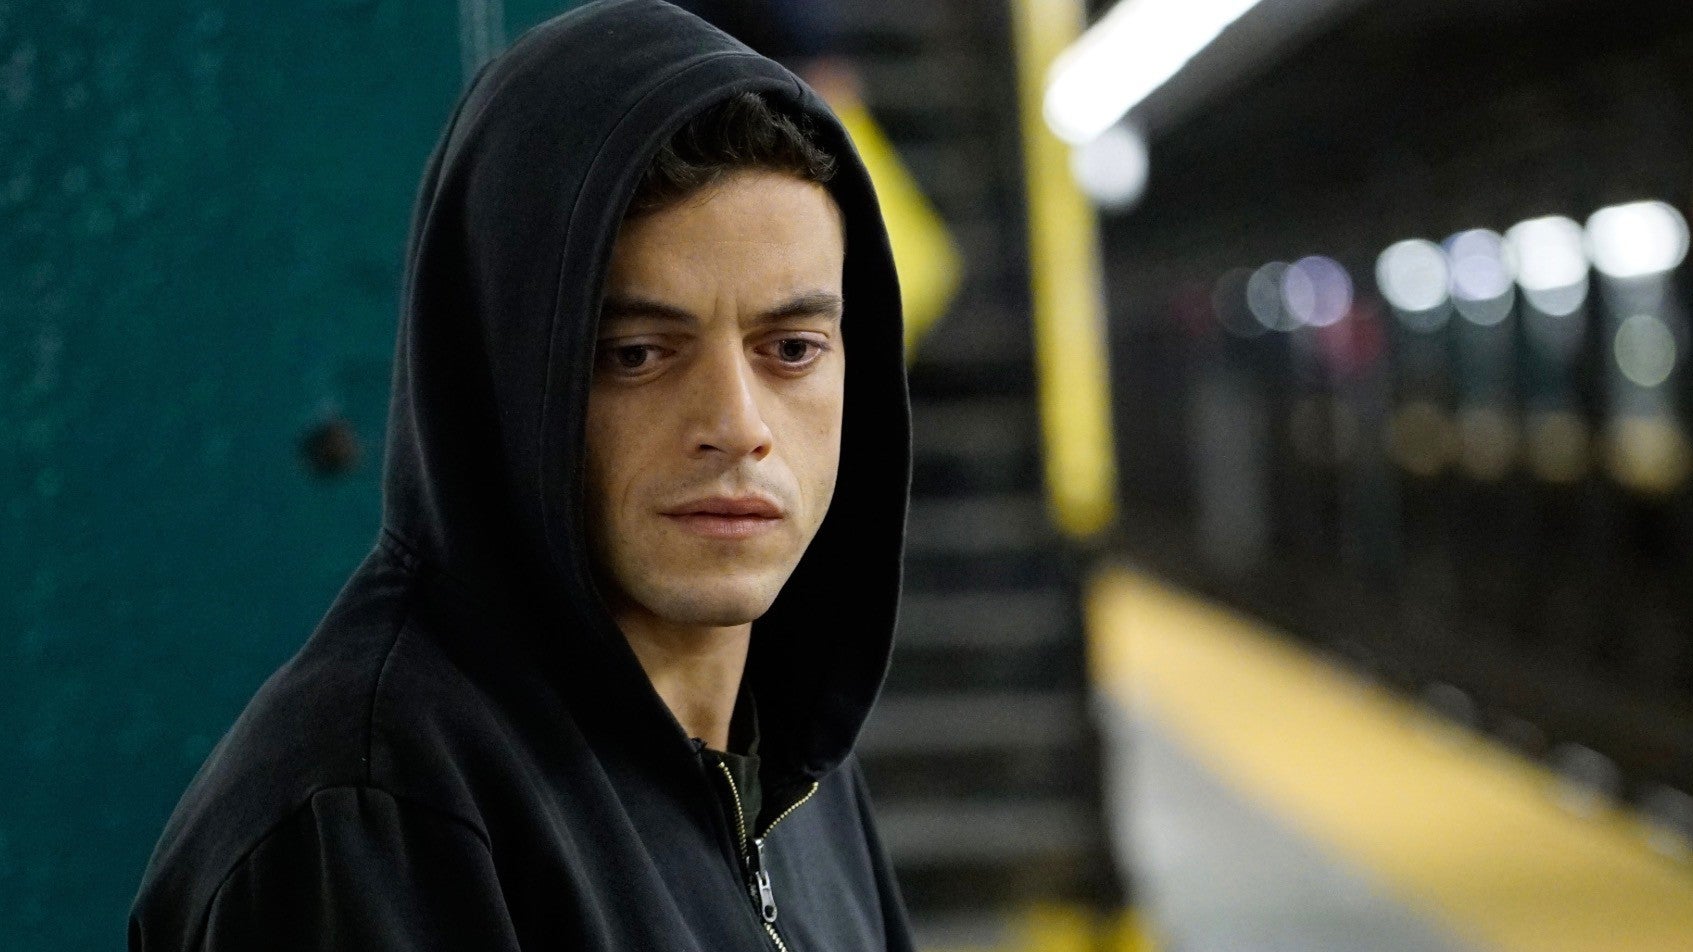
In the TV series Mr. Robot, E Corp CEO Phillip Price treats bitcoin as an existential problem after a after a cyberattack throws the traditional financial system into crisis. “If Bitcoin takes over, we are all in a world of hell,” Price tells a stand-in for a fictionalized U.S. Treasury Secretary. “It is unregulated.”
Price then pitches a regulated alternative, which also happens to be an E Corp product: “With Ecoin we control the ledger… and the mining servers. We are the authority!”
Of course, that pitch is the inverse of what Bitcoin was originally designed to be. A private firm would issue the money and run the accounting ledger, allowing Wall Street and government regulators to maintain control of the financial system. That said, it has become increasingly obvious over the past few years that this is exactly what the greater crypto market was destined to become, and now it’s here.
Circle, the company behind the dollar-pegged USDC stablecoin, launched the closest real-world version of the Ecoin model on Wednesday. The firm opened the public mainnet of Arc, an Ethereum Virtual Machine (EVM) compatible blockchain built with USDC as the unit of account and the asset used to pay fees. The founding validator set is drawn from the institutions that already run large parts of traditional finance: BlackRock, Visa, Mastercard, the Depository Trust & Clearing Corporation, ICE, Standard Chartered, Galaxy, MoneyGram, SBI Group, Sumitomo Corporation, and Global Payments, alongside Circle itself.
— Kyle Torpey (@kyletorpey) September 16, 2026
The similarities between Mr. Robot’s fictional Ecoin and Circle’s real-world Arc are obvious to anyone who has seen the show. Both systems use the blockchain technology popularized by crypto to rebuild the financial sector in a way that maximizes corporate profits and control, while also removing most of Bitcoin’s fundamental value propositions. The core difference is that while Ecoin was the product of a single fictional monopoly, Arc is a collaborative effort between a centralized stablecoin issuer and some of Wall Street’s largest institutions. Both, however, serve as ledgers designed to replace the volatile, unregulated world of crypto with a controlled, dollar-based digital economy. Indeed, Circle refers to Arc as an “economic operating system for the internet.”
Notably, Circle already has the technical ability to blacklist addresses and freeze USDC balances on any blockchain where it is issued. The company has said it will not use that power without a court order or direction from law enforcement, but the backdoor exists. BlackRock is expected to put its BUIDL tokenized money market fund on the network, and banks including BNY, HSBC, Societe Generale, and State Street are listed among early institutional participants.
In Price’s language, the people who control the ledger are not anonymous miners. They are the same names that already clear securities, process card payments, and custody trillions in assets in the traditional financial system.
Crypto Reaches Its Final Form
Arc is what a large part of the industry has been marching toward since Bitcoin’s block size fight roughly a decade ago. While Bitcoin kept a conservative, highly decentralized base layer at the end of the intense technical debate, the camp that wanted cheap transactions and dollar-denominated tokens to attract mainstream adoption moved to platforms such as Ethereum.
Over time, the issuers of stablecoins and crypto exchanges that sit between users and public blockchains gained more leverage and power in those systems. Circle now wants USDC’s settlement layer under its own roof. Coinbase also already routes activity onto its own Base blockchain, and Robinhood launched Robinhood Chain in July for tokenized stocks and other real-world assets.
Notably, at an event in 2016, Circle CEO Jeremy Allaire argued the industry was still early and should not get attached to existing public networks. “It’s highly unlikely that any of us will be using Bitcoin in five or ten years,” Allaire said. “In the same way that — how many of us use NCSA Mosaic or Netscape Navigator?”
Of course, bitcoin did not fade, and it has grown into a digital gold of sorts. What looks shakier is the long-term case for general-purpose chains like Ethereum that became more useful for the U.S. dollar and various centralized institutions than anything else. The obvious point of a USDC-native chain like Arc with Wall Street validators is to pull settlement, fees, and tokenized-asset flow off public networks like Ethereum that currently sit in the middle of that stack. In other words, it makes sense for these centralized players to own and operate as much of the new digital economy’s tech stack as possible.
Circle is explicit about this ambition. Allaire has described Arc as base-layer infrastructure for the future of money, and in an interview with The Rollup, he referred to the launch of Arc as crypto’s iPhone moment. “There were 15 years of people building mobile, massive companies, Microsoft, Nokia, Samsung, the Palm Pilot, the BlackBerry,” he said. “Then came the breakthrough of Android and iOS. These new operating systems created the surface area, the user experience, the developer experience. Enough things converged at the right time. That’s how I think about what we’re doing with Arc.”
Every blockchain before @arc was the BlackBerry, and @circle's CEO @jerallaire is betting Arc is the iPhone moment.
"There were 15 years of people building mobile, massive companies, Microsoft, Nokia, Samsung, the Palm Pilot, the BlackBerry. Everyone thought they had mobile."… pic.twitter.com/FZuX4fj7oV
— The Rollup (@therollupco) September 16, 2026
The product roadmap around these supposedly new systems keeps drifting back toward what very much looks like the traditional, centralized financial system that already exists. As another recent example, one startup pitched the reinvention of credit card chargebacks for stablecoins this past week. Stablecoins and even some of the underlying public blockchains themselves also already have mechanisms for reverting to traditional safety measures, such as freezing assets or reversing the effects of security incidents via centralized backdoors, which raises the question of what the actual value proposition is here.
For now, it seems clear the way crypto is currently regulated has created an opportunity for financial institutions to use this technology to simply avoid regulations, which can lower costs and enable differentiated products for their customers. However, it’s unclear how long the current regulatory environment will last, as the crypto industry’s regulatory clarity bill failed to pass a vote to reach the Senate floor earlier this week. As Trump’s apparent conflicts of interest in the crypto industry come under more scrutiny, more people may begin to question whether this technology is enabling anything useful, and the public’s opinion of the industry could continue to move in a direction that has a negative impact on crypto’s currently allowed regulatory loopholes.